


| Feature | Small Business Insurance | Mid-Market Commercial | Enterprise & Specialty |
|---|---|---|---|
| Best Suited For | Retailers, independent contractors, local offices | Mid-sized manufacturers, wholesalers, multi-location companies | Multinational corporations, heavy industrial, specialty risk sectors |
| Typical Scale | Under $10M in revenue; local operations | $10M to $100M+ in revenue; multi-location or complex operations | Multinational scale; heavy industrial |
| Policy Structure | Bundled "Business Owner's Policy" (BOP) | Tailored, multi-line commercial packages | Custom-engineered risk portfolios |
| Risk Management | Standard liability and property coverages | Access to dedicated Risk Services & Loss Prevention Engineers | Complex loss-control, captive insurance, and risk engineering |
Economical is becoming Definity Insurance.
Same commitment, new look.
What does business insurance cover?
Business insurance, also known as commercial insurance, helps protect Canadian companies from financial losses related to unexpected events, lawsuits, or property damage. Economical offers tailored commercial property and auto, general liability, and other options to help protect your business assets, employees, and operations against industry-specific risks.
What types of business insurance do you need?
A comprehensive commercial insurance package combines different coverages tailored to your business needs and size. Economical Insurance offers:




What level of commercial coverage do you need?
Commercial insurance tailored to your industry
We can tailor coverage based on the risks that your industry faces, including:
Ready to get started?
Contact your broker to learn more about business insurance options that fit your needs.

Bearing fruit: how Kirk’s policy came through for him after a blaze that threatened the family’s apple farm
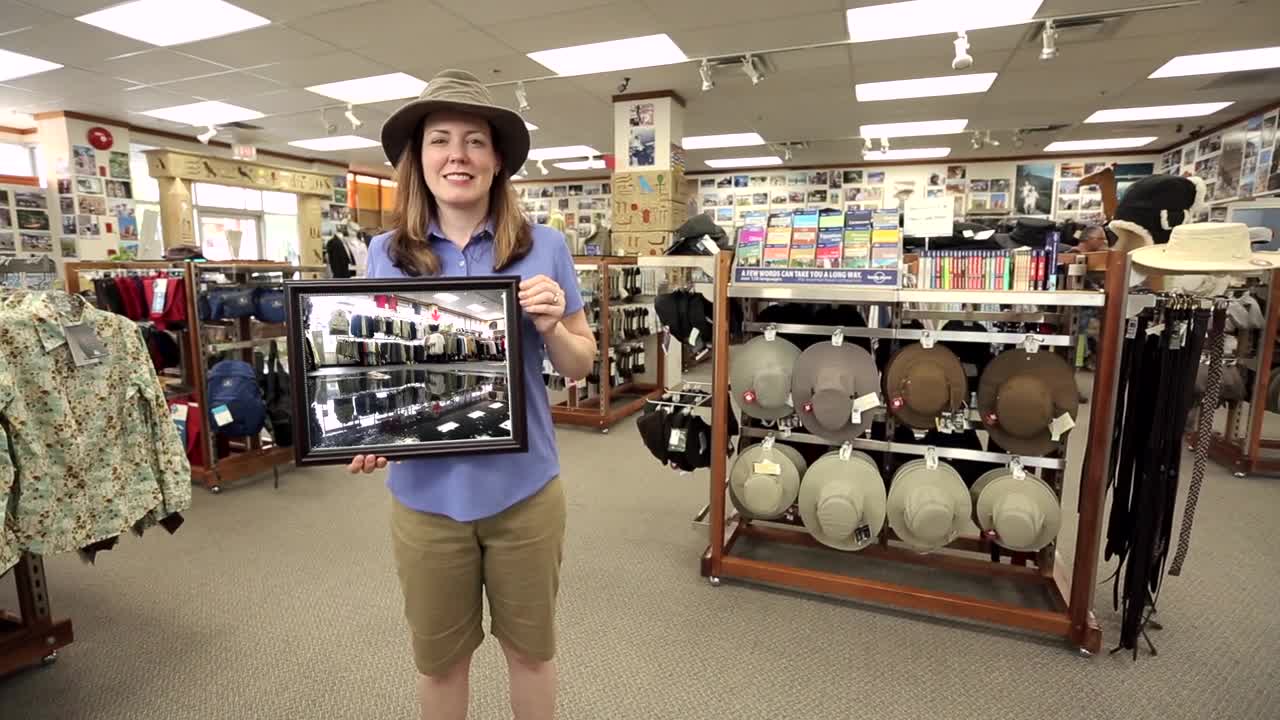
After the flood: how we helped a Vancouver hat shop dry off and return to business as usual

Frequently Asked Questions
No.
Most home insurance policies exclude business activities, including liability claims and business equipment. If you run a business from home, you need either a home-based business endorsement or a separate commercial insurance policy to make sure you’re properly protected.
A BOP bundles essential coverages into one policy. It usually combines:
Commercial General Liability (CGL)
Commercial Property Insurance
It's often a good fit for smaller, lower-risk businesses looking for simple, combined protection.
Yes, in most cases, even if it’s not legally required.
While business insurance isn’t universally mandatory, certain coverages may be required depending on your situation, such as:
Commercial Auto Insurance (required by law if you use vehicles for business)
Liability insurance (often required by landlords, clients, or contracts)
Professional Liability (required by many professional associations)
Even when not required, insurance helps protect your business from costs that could otherwise be difficult to recover from.
The difference is complexity and customization.
Small business insurance
Typically offers packaged coverage with core protections like liability and property, designed to be simple and easy to manage.
Mid-market commercial insurance
Designed for businesses with more complex operations, higher exposure, or multiple locations. These programs are more tailored, often include higher limits, and can come with additional risk expertise and support.
There’s no one-size-fits-all answer.
Your premium depends on factors like:
Industry and type of work
Business size and revenue
Location(s)
Claims history
Coverage limits and deductibles
A small business might pay a few hundred dollars per year, while larger or higher-risk operations will typically pay more based on their exposure.
Commercial insurance can help protect your business from:
Liability claims (injury or property damage)
Damage to your building, equipment, or inventory
Lost income if your business is interrupted
Cyber incidents or data breaches
Claims related to professional services or business decisions
Reviewed by Definity Insurance Commercial Underwriting Team | Last Updated: August 2026